Navigating Retail Display Procurement Amid China’s Economic Slowdown
According to Nikkei Asia, slower consumption and a sharper fall in property investment across August pushed the Chinese economy deeper into a quagmire, leaving exports as the key growth pillar and…
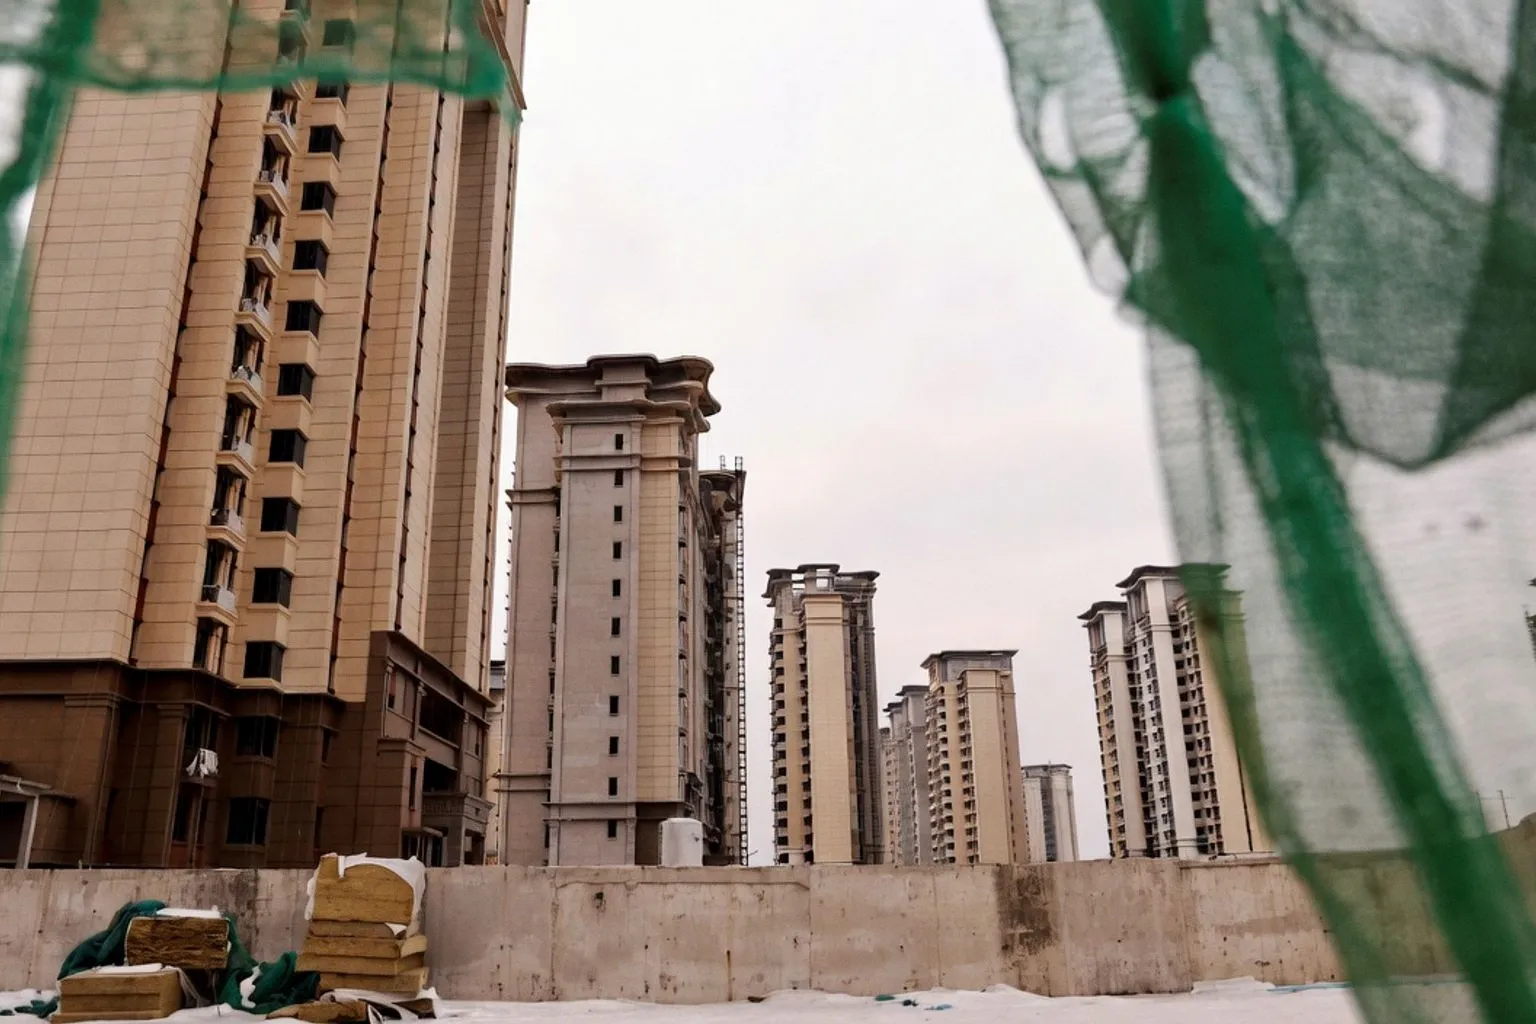
According to Nikkei Asia, slower consumption and a sharper fall in property investment across August pushed the Chinese economy deeper into a quagmire, leaving exports as the key growth pillar and piling pressure on policymakers to deliver fresh stimulus. For anyone selling or specifying commercial display systems, this is the signal to tighten your assumptions before you commit to next year's capex.
What a softer Chinese retail cycle does to your racking order book
When consumption cools at the scale Nikkei is describing, the second-order effect on our world is rarely the obvious one. We do not see fixtures fly off the loading dock the way consumer electronics do. What we see is a longer runway on quote-to-install, more requests to redesign around existing shelving rather than rip-and-replace, and a quiet shift in SKU density conversations as merchandisers try to do more with the same linear feet. If you are a display rack supplier or in-house retail space planner watching Asian demand, expect procurement teams to push harder on modular systems and reconfigurable gondola runs. They want flexibility because nobody on their side can promise what the second half of next year looks like.
The property side matters just as much. A property investment downturn means fewer new mall openings, fewer anchor-tenant buildouts, and a longer tail on every expansion project already in your pipeline. Practically speaking, that is fewer greenfield fixture orders and more retrofit work, which is a different margin profile and a different installation cadence. Walk your accounts before they call you. If a chain had been talking about a flagship rollout, now is the moment to ask what the fallback floor looks like and whether you can deliver a phased planogram refresh instead of a full refit.
Where to focus the conversation on the floor
When the macro picture gets noisy, we earn our keep by tightening the link between fixture decision and a measurable KPI. Two questions to bring to your next walk-through.
First, dwell time at the endcap. If foot traffic is softer, the endcap stops being decoration and starts doing the heavy lifting on conversion. Review your current endcap assignments with the merchant team and ask which ones are pulling their weight and which are just taking up sightlines from the main aisle. We have all seen endcaps that look beautiful and sell nothing while the wall behind them does the real work.
Second, sightlines from the entrance. Soft consumer confidence rewards stores that lead the eye cleanly to a hero category within the first three seconds of walking in. That usually means simplifying the first run of gondola, lowering the top shelf so the back wall reads, and making sure the lighting actually hits the merchandise instead of the ceiling. None of that requires new racking. It requires a sharper planogram conversation.
What to watch through the rest of the year
Keep an eye on three things from this story. First, whether Beijing rolls out a consumer-facing stimulus package or sticks with export-side support, because the first path puts discretionary retail back in play and the second does not. Second, any data out of China on new store openings and mall completions, since that is the leading indicator for fixture demand three to six months out. Third, your own sell-through by category. When a macro story like this lands, the retailers who weather it best are the ones who adjusted planograms two quarters earlier, not the ones who waited for the numbers to turn.
The headline is global, but the work is on your floor this week.